


When enrolments fall, a leasing operator faces a particular kind of financial pressure. Revenue drops, but rent does not. That gap between a cost that is fixed and an income that is not is where the vulnerability of leasing becomes most visible. And in 2026, with oversupply emerging in some childcare catchments, more operators are starting to feel it.
Even Australia's largest childcare operators have felt these pressures in 2026. Embark Early Education reported softer demand and falling EBITDA in the first half of the year, pointing to increased supply in some catchments. Earlier this year, G8 Education suspended 40 centres citing falling demand and changing operating conditions.
The size of these operators means that they have resources that most independent operators do not have. Yet, both still found local oversupply difficult to absorb.
Oversupply is a local problem, not a national one
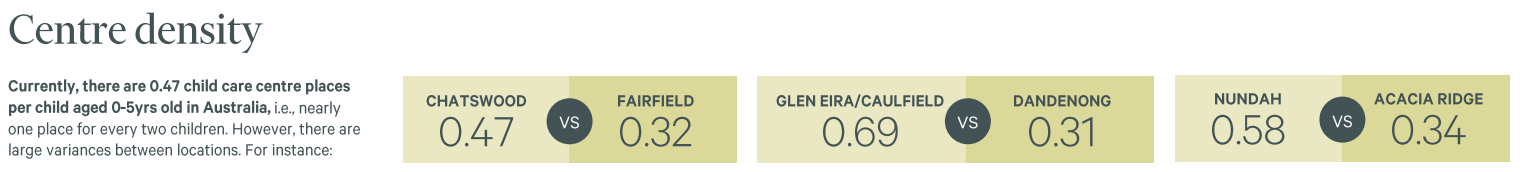
The centres facing the most pressure in 2026 appear to be those in catchments where new supply has grown faster than local demand. According to CBRE, there are 0.47 childcare places for every child under five nationally, but that figure conceals big variation at the local level.
For example, in Melbourne, Glen Eira/Caulfield sits at 0.69 places per child while nearby Dandenong sits at 0.31. In Sydney, Chatswood is at 0.47 while Fairfield is at 0.32.
CBRE also estimated that new supply ran at approximately 30,000 places per year in the 24/25 financial year, concentrated in metro areas. In catchments where that supply has landed, operators are feeling the effects. Elsewhere, centres in undersupplied areas continue to perform well.
This is clear evidence that what matters most is not the national picture – it is what is happening in the suburb where your centre operates.
What does softening occupancy mean for operators who lease?
When a centre sits in one of those oversupplied catchments, the gap between fixed costs and falling revenue becomes real quickly. Rent continues regardless of how many children are enrolled, and you absorb the entire impact of demand softness while your landlord does not.
If conditions deteriorate to the point where your centre becomes unviable, your choices narrow quickly. Exiting a lease typically comes at a high cost. Continuing to operate at a loss is probably not a viable strategy. And at the end of either path, you leave with no asset to show for the years spent building the business.
Large operators, like G8 and Embark, have the scale and resources to navigate this; most independent operators do not.
Ownership changes that
An owner-operator facing the same occupancy pressure is in a fundamentally different position. The property you own retains value, regardless of how the business is performing at any given time. A well-located freehold childcare property has an underlying land value, an established licence and the potential to be used as something else – none of which disappear because enrolments have softened.
That gives you options that a leasing operator simply doesn’t have. You can choose to lease the premises to another business, sell the property or hold the asset while working through the business challenges.
Your decisions about your property and the business remain separate, offering you a form of financial resilience a leasing operator doesn't have.
For independent operators who lease, the margin for error is smaller and the options are fewer. Ownership does not change the local supply picture, but it can change what you as an operator can do if demand shifts.
Ligo Finance works with childcare approved providers to structure the finance that makes ownership possible. If you are currently leasing your premises, get in touch to find out what your options look like.


